Cannabis operators watching the rise of AI purchasing agents in mainstream retail should pay close attention to a question that has quietly moved upstream of the checkout counter: who decides whether an agent is even allowed to pay. That question is being answered right now by banks, payment networks, and software platforms outside cannabis entirely - but the structure they're building will land squarely on dispensary POS systems, wholesale ordering platforms, and B2B cannabis payment rails sooner than most operators expect.
The Authorization Layer Is the New Chokepoint
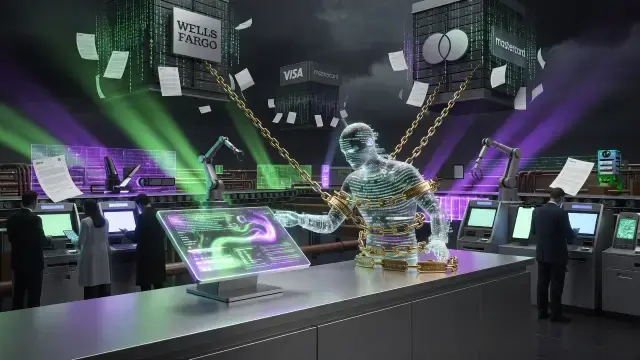
In mainstream finance, major banks have spent the past weeks restricting AI agents from initiating transactions, while payment networks and credential platforms build registries, scopes, and tokens that decide in advance what an agent can and cannot do. The transaction itself is no longer where the decision happens. The decision happens earlier - in a contract clause, a directory registration, a minted credential - and whoever owns that artifact controls the money. For an industry still locked out of conventional banking relationships in many states, this matters. Cannabis retail already runs on a patchwork of cash handling, cashless ATM workarounds, and closed-loop payment apps because federal banking restrictions keep traditional processors wary. If agentic commerce becomes the default layer for B2B ordering - wholesale buyers automating reorders from distributors, dispensaries automating replenishment against METRC inventory counts - the question of who issues the authorization credential becomes a compliance question, not just a technology question.
What This Means for Compliance and Seed-to-Sale Systems
Dispensary operators rely on seed-to-sale tracking, COA verification, and license-level purchase limits to stay compliant at the point of sale. An automated purchasing agent acting on behalf of a retailer or a consumer introduces a new layer that regulators have not yet addressed: who is responsible when an agent executes a purchase that violates a daily possession limit, buys from an unlicensed wholesale source, or bypasses age-verification controls built into a dispensary's point-of-sale terminal? In conventional retail, the emerging answer is that liability follows the authorization artifact - the bank's contract language, the registered scope, the token's lifetime - rather than the transaction itself. Cannabis compliance teams should treat that as a warning sign. A state regulator auditing a licensee's sales records is not going to accept "the agent was authorized upstream" as an answer to a compliance log that doesn't reconcile. Inventory shrinkage, batch tracking, and tax reporting under 280E all depend on knowing exactly who initiated a transaction and when.
Operational Risk for Multi-State Operators and Payment Vendors
Multi-state operators building wholesale menus and B2B ordering platforms should watch how networks like Visa and Mastercard are structuring agent enrollment - by directory registration, by scope, by token - because that same architecture will eventually reach cannabis-adjacent payment processors and ordering software. Here's the catch: cannabis already operates under tighter scrutiny than almost any other retail category, so a loosely governed agent authorization system built for mainstream commerce may not translate cleanly. Payment vendors serving the plant-touching supply chain need contract language - similar to Wells Fargo's approach of deeming agent-initiated transactions pre-authorized - that clearly assigns liability before any automated purchasing tool touches a wholesale order or consumer transaction. Landlords, software vendors, and compliance officers should ask vendors now: who holds the authorization artifact, and what happens when it's wrong?
- Authorization now happens before the transaction - in contracts, registries, scopes, and tokens - not at the point of sale.
- Cannabis compliance systems depend on knowing exactly who initiated a purchase; upstream authorization complicates that record.
- Liability in agentic commerce is following the artifact that grants permission, not the transaction itself - a structure cannabis payment vendors should study before adopting agent-based tools.
- Multi-state operators and POS vendors should demand clear contractual answers on agent liability before enabling automated purchasing or reordering.